Week of Sept 5 Weekly Recap & The Week Ahead
1. Private payrolls rose by 38,000 in August, less than expected, ADP reports — The payrolls processing firm said firms added 38,000 workers, fewer than the upwardly revised 46,000 in July and below the Dow Jones consensus estimate for 47,000. Though job creation held positive, August was the smallest gain since January and reflective of a broader slowdown in the labor market. Moreover, most of the jobs came from three sectors, with multiple others showing declines. Leisure and hospitality added 16,000 positions and construction was up 12,000. Outside of that, though, there were few growth areas. Manufacturing lost 17,000 jobs, professional and business services was off 16,000, and both natural resources and mining as well as trade, transportation and utilities reported declines of 5,000.
2. US Trade Gap Widens on Import Surge — The gap in goods and services trade grew 24.4% from the prior month to $88.6 billion, according to the Trump administration. The rapid rate of technology imports reflects the investment race in artificial intelligence, a key driver of current US economic growth. While many of Donald Trump’s tariffs, levied as part of his ongoing trade war, were struck down as unconstitutional earlier this year, the president is using other authorities to impose duties (moves which also have triggered litigation). Most recently, the US levied 50% duties on billions of dollars of Canadian goods, and Canada retaliated after trade talks fell apart last month. Meanwhile, the value of outbound US shipments of industrial supplies such as oil and petroleum products declined, according to the Commerce Department. Exports of non-monetary gold also fell. Trade in this category has been particularly volatile since early last year.
3. US Adds 162,000 Jobs, Topping All Estimates in Broad Advance — Nonfarm payrolls increased 162,000 last month and July’s job losses were revised away, according to Bureau of Labor Statistics data out Friday. The August increase topped all estimates in a Bloomberg survey. The unemployment rate remained at 4.1%. The broad advance in payrolls was led by a rebound in leisure and hospitality employment following big declines in June and July. Local government education also added about 42,000 jobs following outsize cuts last month. That category can be volatile in the summer as many teachers fall off of payrolls before returning again as the school year begins. Manufacturing payrolls rose by the most since 2023, while construction firms added the most jobs since January. Many economists have pointed to the data-center buildout as a driver of demand for construction labor this year.
The financial activities and information sectors — both of which are seen as particularly exposed to AI-related job displacement — shed a combined 34,000 positions.
4. U.S. Trade Deficit Widened in July — U.S. imports were higher than exports by $88.6 billion, versus $71.2 billion in June. Analysts polled by The Wall Street Journal were expecting a $90 billion deficit. The gap is the result of imports increasing 2.8% in July from the previous month, to $399.3 billion, while exports decreased 2.1% to $310.7 billion.
Imports of goods increased $11.4 billion in July, while exports of goods decreased $6.2 billion. Exports of crude oil decreased $4.5 billion. International commerce has been affected by volatile tariffs that put the U.S. at odds with traditional trade partners. More recently, negotiations with Canada have failed to yield a deal, opening the door for steep levies from both sides. Wars in the Middle East, Russia and Ukraine are also disrupting energy and food trade.
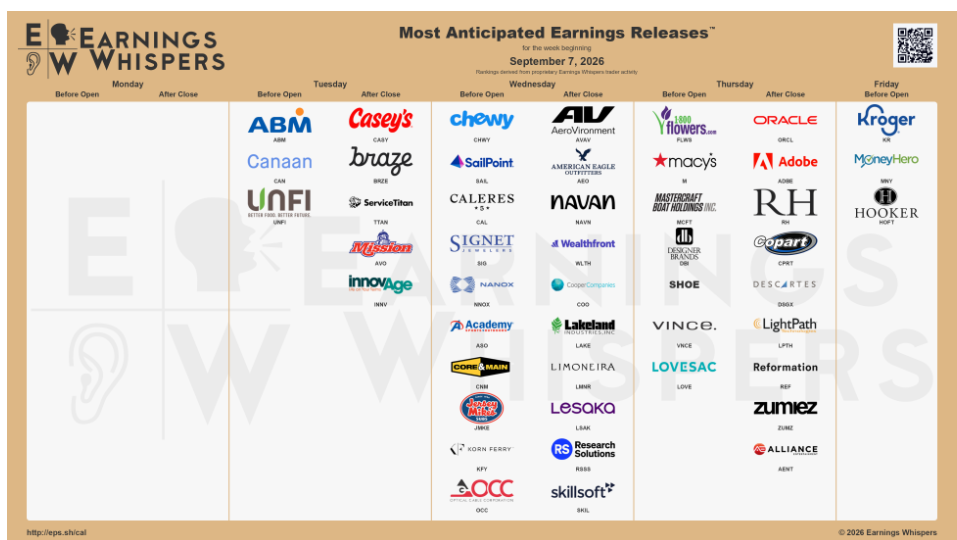
strong>The week ahead — Economic data from Econoday.com:
 This entry was posted
on Thursday, September 10th, 2026 at 5:38 pm and is filed under Weekly Summary.
You can follow any responses to this entry through the RSS 2.0 feed.
You can leave a response, or trackback from your own site.