Week of Oct 4 2026 Weekly Recap & The Week Ahead
“The market doesn’t reward the smartest traders. It rewards the most disciplined ones.”
1. US 30-Year Treasury Yield Rises to Highest Level Since 2002 — The 30-year rate surpassed 5.59% on Tuesday to touch a level last seen in 2002, in the wake of the dot-com bust. The latest leg higher came as elevated energy prices added to inflationary pressures and hefty corporate-debt supply weighed on the market. It’s latest in a series of milestones for the $32 trillion Treasuries market, which is in the throes of a months-long selloff. Government debt has been flailing around the world as elevated oil prices — tied to the war in the Middle East — ripple through the global economy, pushing investors to bet central banks including the Federal Reserve will further raise interest rates.
2. US Consumer Confidence Plunges to Lowest Level Since 2014 — US consumer confidence fell in September to the lowest level since 2014 as views about the economy and the labor market deteriorated. The Conference Board’s gauge of confidence decreased 6.7 points to 81.9 after a downward revision to the prior month, data released Tuesday showed. The figure was well below all expectations in a Bloomberg survey of economists. US consumer confidence fell in September to the lowest level since 2014 as views about the economy and the labor market deteriorated.
The Conference Board’s gauge of confidence decreased 6.7 points to 81.9 after a downward revision to the prior month, data released Tuesday showed. The figure was well below all expectations in a Bloomberg survey of economists.
3. Growth, Inflation Figures Show Signs of an Economic Pickup — according to WSJ, The Commerce Department raised its reading for annualized gross domestic product growth in the second quarter to 2.2%, well above the 1.5% that had previously been reported. The key consumer-spending and investment categories were both stronger than previously thought. A key metric of underlying growth trends, real final sales to private domestic purchasers, was also tweaked higher, to 4.6%. In August alone, price increases accelerated. The overall index rose by 0.3%, and the core version that excludes food and energy prices rose by 0.2%, faster than the July readings.
4. Jobs Growth Much Weaker Than Expected in September; Unemployment Ticks Higher == After uncharacteristically strong payroll gains in August, hiring was more on trend in September with a gain of just 29,000 jobs. That was dramatically below expectations, but not far off the average monthly gain of 45,000 experienced over the past year. The unemployment rate ticked up to 4.2% in September, from 4.1% the previous month. While that may seem problematic at first glance, the rise was generally the result of stronger labor participation and growth in the labor force. Monthly wage growth proved very subdued, rising just 0.1% in September. That’s a good sign that the labor market isn’t boosting inflationary pressures, but a tough break for the many Americans struggling with higher costs of living.
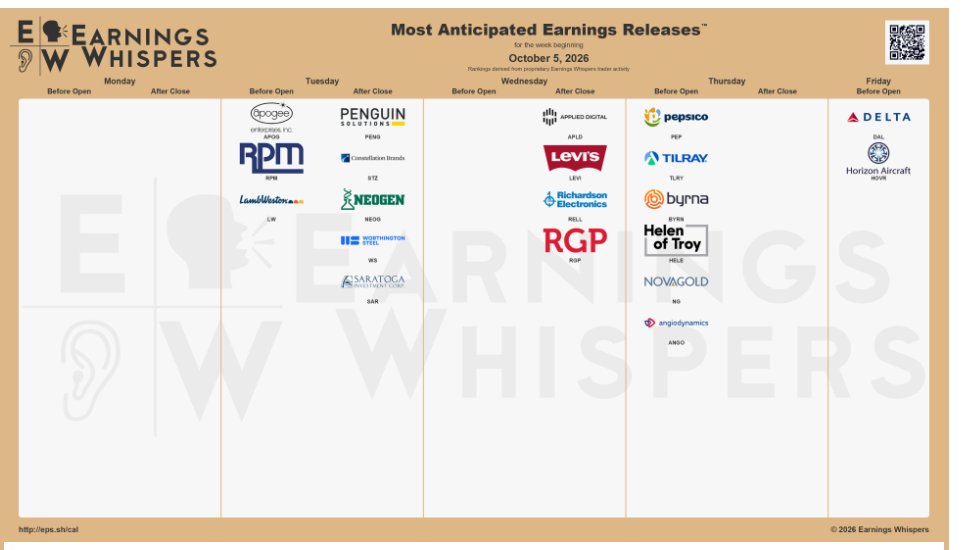
strong>The week ahead — Economic data from Econoday.com:
 This entry was posted
on Wednesday, October 7th, 2026 at 5:54 pm and is filed under Weekly Summary.
You can follow any responses to this entry through the RSS 2.0 feed.
You can leave a response, or trackback from your own site.